Posts

Showing posts with the label mortgage advice

FTC Rule Bans Up-Front Fees for Modifications

FTC Rule Bans Up-Front Fees for Modifications DS News just informed me, that "The Federal Trade Commission has proposed a new rule that would prohibit third parties, including loan modification specialists and loss mitigation attorneys, from collecting payment for foreclosure prevention services until after they obtain a documented offer from a lender or servicer for a modification or other form of mortgage relief." I think this is great news. You know I'm against anyone paying anyone for a loan modifification, since it's something anyone can do on their on. However, if they choose to be lazy, than ayone taking on the task should only be paid for accomplishing a loan mod, not just faxing over income and asset documentation. I'll be keeping my eye on this one. Cheers, Sunil www.sunilsethi.com
Who Says there's no free mortgages - Bank pays the price for Poor Record Keeping

A judge in New York wiped out the debt on a home because the lender failed to show ownership of the loan. This sort of action would wipe out the securitization market. Who’d want to buy an investment that could be wiped completely because of poor record keeping. -sunil SMA REALTY Sunil Sethi / Associate Broker, REALTOR, MBA, CPA / SMA Realty 38350 Fremont Blvd. #202 / Fremont, CA 94536 Office 510 793 8600 / Mobile 510 388 2436 / Fax 510 431 9046 Personal: http://www.sunilsethi.com blog: http://fremontrealestate.blogspot.com/ LinkedIn: http://www.linkedin.com/in/fremontrealtor

0.5% down will get you this house. - What a stupid idea!

I was reading John Occhui's post The Next Wave of Bad Loans - Option Arms This is not new news; this is a rehash of what has been said about Option ARMS since the beginning. My tag line that I print on my business card and had on my website during the go-go years was, "Friends Don't Let Friends Buy Options ARMS." I once had a booth at the Fremont Art and Wine Festival, with a big poster with my tag-line, and all the mortgage brokers that passed by laughed because they understood what it meant, but they'd loved the money they were making off option ARMs. With the exception of the little old blind ladies, there is no sympathy here for borrowers, you were focused on your cash-out and paid no heed to the consequences. If you take a loan with a variable element, you have to be prepared to deal with the variable when it happens. At an open house last week, a mortgage broker came by all excited because he now was offering an FHA with only a 0.5% down payment. I asked him...

Guidelines coming soon for Fannie Mae's DU Refi Plus Program

See below: Got this from one of my wholesale lenders: Information Regarding Making Home Affordable Initiative with Fannie Mae's DU Refi Plus TM Program and the New Agency and Agency Plus Loan Limits Making Home Affordable with Fannie Mae's DU Refi Plus Program Mortgage Company. is pleased to support the "Making Home Affordable Initiative" announced last week which includes the DU Refi Plus program. Working closely with Fannie Mae, Mortgage Company is finalizing credit guidelines and system enhancements to make the DU Refi Plus program available beginning April 4, 2009. The goal of this new refinance option is to provide expanded opportunities for borrowers who have demonstrated an acceptable payment history on their Fannie Mae owned or guaranteed mortgage but have not been able to refinance due to declining property value or an inability to obtain mortgage insurance. Although formal applications may not be taken at this time, Wholesale lenders should encourage custom...

Should you buy today or wait for further decreases in home pricing

Image
A client I worked with this last weekend, got me to thinking about how I should look at this problem. It’s all going to boil down to what you think will happen with: Your income stream (job security, ability to get another job, if your company decides it needs to downsize, etc.) Mortgage Interest Rates Property Values Obviously, renting is the safer, securer option for you right now, but the benefit of owning is that you fix your housing costs (since a 30 yr mortgage is major component of your home ownership costs, taxes are limited to increasing at 2% (California’s Proposition 13), and insurance rates have actually come down the last 2 years). I don’t think pricing will move up the next year. However we don’t know where interests maybe. One concern out there is that interest rates will be higher in the future because of money the government is printing right now will cause inflation. So the big benefit of buying today is that rates are low, and pricing is also very good. Take a look a...

It Does Make Sense to Pay a Point

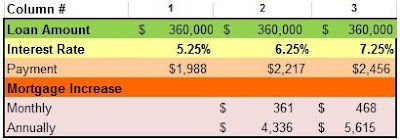
It used to be that the difference between a no-cost and cost refinance was about a .25% however today the difference can be as high as 1%. So consider both options in deciding which way to go. The math basically involves determining how long it’ll take to recover your upfront costs. If it’s less than 2-3 yrs, and you plan to stay in the home for at least 5+ yr, than consider paying the costs.

Will we ever see the mystical 4.5% rate. One Major lender says no!

Image
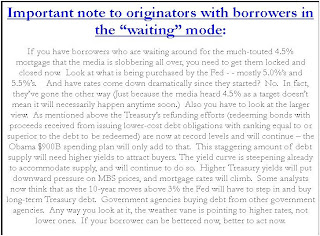
The analysis seems right. I don’t think we’ll see the mystical beast of 4.5% 30yr fixed interests rates, the way the govt is spending money, which has to be financed.

FW: HOPE for Homeowners Program Will Not Be Eligible Through Our Third Party Lending

I received this information from a lender regarding the HOPE Mortgage Program. It doesn't look that promising but I would definitely investigate it. If you are interested in finding out more you have to contact your lender’s customer service department. Please share your experiences here. -sunil Housing Finance Reform Title IV HOPE FOR HOMEOWNERS Creation of a new FHA Loan Program “HOPE FOR HOMEOWNERS PROGRAM” (aka FHA Rescue): (Page 394) · The purpose of the Program it so insure refinanced loans for distressed Borrowers; allowing owner occupant homeowners to avoid foreclosure by reducing their principal outstanding balance and their current interest rate; ( think of a short sell refinance ) . I am not aware of any Lenders that will pay an origination fee, when they are taking a significant loss of the loan to start. Lost principal that will be absorbed by the bank, possibly the Federal government if that comes out of our latest housing Bill on the floor. Not likely. · The Bill a...

non-conforming jumbo - Rate-Term vs. Cash-out

I spoke out the $100,000 limit on the cash-out conforming jumbo recently. Let me share something one Chase lender rep just sent me. Borrower had purchase money 2nd HELOC (the money used to buy the house). The borrower went back to SAME lender to modify from HELOC to a fixed loan. No cash was drawn. Lender issues new loan number, a new note and records a new deed. Now he's trying to refinance the 1st and 2nd into a new conforming jumbo. The new loan was submitted to Chase as a rate-term refinance because the existing 1st and 2nd were purchase money loans. Chase's Underwriter countered the loan to be treated as a cash-out refinance as the current 2nd was no longer a purchase money, because it had a new loan #, note and deed or trust. The broker and I pushed all the way up Chase Management and the answer was no. Then I had the broker call FNMA and when we got a positive answer asked Chase to call FNMA to confirm. FNMA said if the broker can provide the purchase money HUD1 and the ...

Hybrid ARMs

Every week some new bank rep will come to my office telling me about their bank, and their products. Most of these folks are usually pitching sub-prime products (how low a FICO score they can qualify for) or Option ARMs (how many points I can make originating them). In the end I usually give them my business card and ask them to read my tag line on back of the card -"Friends Don't Let Friends buy Option ARMs ". Well, a couple of months back, a rep came in talking about a new product called a Hybrid ARM. On the surface a H ybrid ARM sounds great - (the marketing guys, who came up with the name, probably thought they could ride-share on the euphoria over Hybrid cars). Well in this case what you're buying is an Option ARM with a fixed rate. The argument these reps always gave me about Option ARMS, was that you get four options- 1. the option to pay the low monthly payment calculated using start rate of 1%-1-1.75% 2. the option to pay interest only 3. the option ...